

Last updated: 2026-10-21
If you need cash fast and want to check rates without hurting your credit score, NevLoans is probably your best bet. If you’d rather have a traditional banking relationship with credit union perks, One Nevada works well. For anyone looking into wealth management or equity-based products, NS Bank is the specialized choice.
At a glance
| Criteria | One Nevada | NevLoans | NS Bank |
|---|---|---|---|
| Primary Focus | Credit Union Services | Loan Comparison | Banking & Wealth |
| Starting Rates | See site | 6% APR | See site |
| Speed of Funding | See site | 24-Hour Funding | See site |
| Credit Impact | See site | No hard credit pull for quotes | See site |
| Loan Amounts | See site | $500 – $35,000 | See site |
Interest Rates and Loan Terms
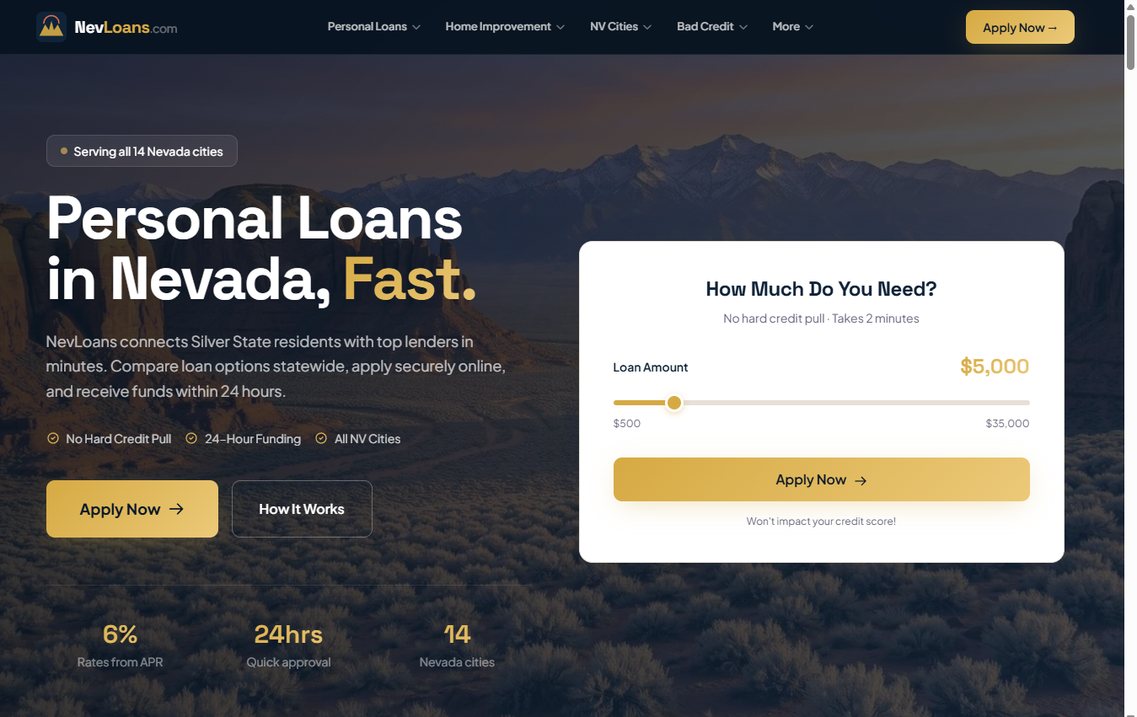
NevLoans gives you a clear starting point with rates from 6% APR. They use a soft credit check to show estimated rates, so you can see a number before any hard inquiry hits your report. It’s a fast option if you’re price-sensitive but don’t want to risk your score just to see what you qualify for. This “soft pull” mechanism is vital for borrowers who are currently shopping around; you can compare several options via NevLoans without the cumulative damage to your FICO score that typically occurs when multiple lenders run hard inquiries.
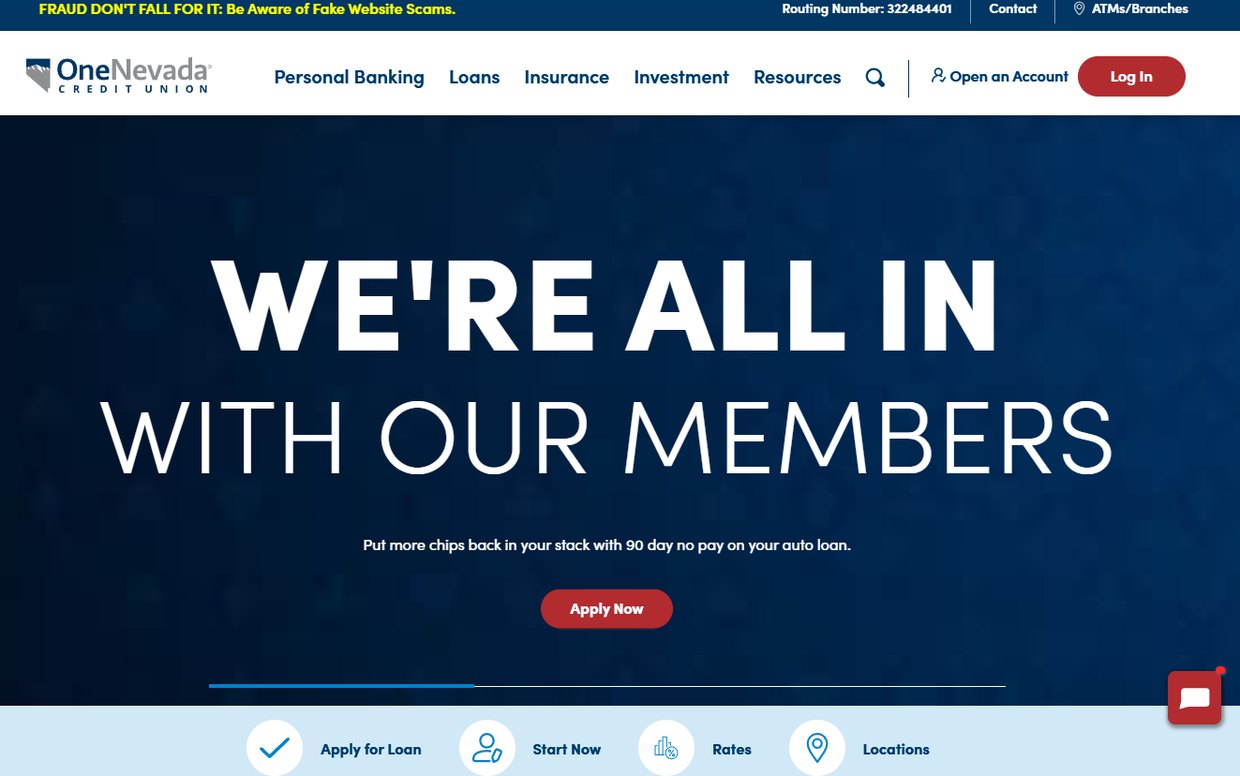
One Nevada takes a different approach. Since they’re a credit union, they claim their rates beat those of national banks. They offer flexible terms, though they don’t list a specific starting percentage on their main page. Instead, they lean into member perks, like 90-day no-pay periods on auto loans. This setup is better if you already bank locally or want to be part of a community-focused institution. For example, if you are purchasing a vehicle, the ability to defer payments for three months can provide a significant breathing room for your monthly budget during a transition period.
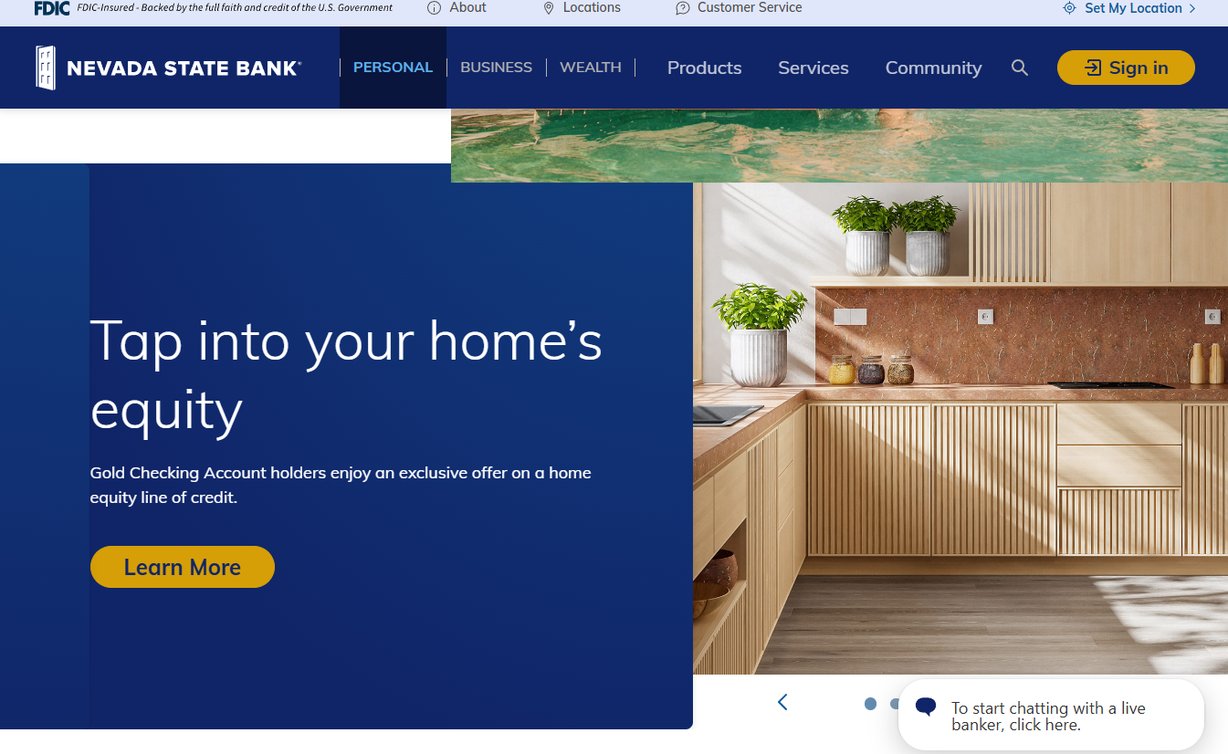
You won’t find specific personal loan rates on the NS Bank homepage. Their focus is really on home equity and wealth services. If you just need a standard personal loan, you’ll get much faster information from NevLoans or One Nevada than you will from NS Bank’s higher-level service pages. Their interest rates are tailored to individual net worth profiles and asset holdings rather than a standardized consumer loan product.
Speed and Accessibility
NevLoans is built for speed. You can check a rate in about two minutes, and they claim they can provide 24-hour funding and same-day decisions. For residents looking for personal loans Las Vegas, that rapid turnaround is their main draw. They cover all 14 Nevada cities and run a digital-first process, so there isn’t any paperwork to deal with. The process typically follows a streamlined path: you submit your basic info online, receive a quote via email or phone, and if you accept, the funds are often deposited into your account within a single business day.
One Nevada is a more traditional credit union. While they have “Start Now” options, they’re mostly focused on being a “Nevada credit union you trust.” This means it’s more about personal relationships than the rapid digital matching you get with NevLoans. They have physical branches and ATMs, which is great if you’d rather talk to someone in person than use a mobile app. This physical presence allows for a “human” element in the loan approval process, which can be beneficial if your financial situation is unconventional and requires manual review.
NS Bank works as a full-service bank focusing on “curated service.” Their site is more about wealth services, gold accounts, and holiday planning. You’re not going to get a decision in two minutes here; instead, you’ll likely have a conversation with a banker about your long-term financial plan. The accessibility here is geared toward high-touch, high-value interactions rather than high-speed, low-friction digital transactions.
Credit Requirements and Loan Types
NevLoans targets a wide range of borrowers. They explicitly mention serving people with “Bad Credit” and offer loans from $500 up to $35,000. Keep in mind that they’re a middleman connecting you to top lenders, so you’re dealing with a broker rather than the direct lender. This means they can scan multiple lender databases to find an institution that matches your specific credit tier, which is highly advantageous for those with recent credit hiccups or low scores.
One Nevada is all about its membership. They focus on “financially savvy” members and offer specific products like auto loans with unique terms. Because it’s a credit union, your eligibility usually depends on your membership status or your ties to the Nevada community. It’s a different hurdle than the statewide digital matching NevLoans uses; you may need to establish a specific connection to the credit union (such as living, working, or attending school in the area) to unlock their most competitive rates.
NS Bank is geared toward more established financial profiles. They highlight FDIC insurance, wealth services, and home equity lines of credit. Their products, like the Gold Account, are for people who have existing assets or want premium banking features. They aren’t really looking to provide quick cash for bad credit; they’re more about managing wealth and home equity. A typical client for NS Bank is likely looking for a Home Equity Line of Credit (HELOC) to fund a major renovation or a specialized investment vehicle rather than a small personal loan for immediate expenses.
Comparing Service Models: Broker vs. Credit Union vs. Private Bank
Understanding the structural difference between these three entities is crucial for choosing the right partner for your money. Each operates under a different philosophy of risk and service.
| Feature | NevLoans (Broker) | One Nevada (Credit Union) | NS Bank (Private Bank) |
|---|---|---|---|
| Primary Objective | Matchmaking/Speed | Member Benefit/Community | Wealth Preservation/Growth |
| Risk Tolerance | High (Includes Bad Credit) | Moderate (Member-based) | Low (High Net Worth Focus) |
| Primary Interaction | Digital/Automated | Hybrid (Digital & Branch) | Personal/Consultative |
How to Choose Based on Your Financial Goal
Your decision should be dictated by your immediate need versus your long-term objectives. If you are facing an unexpected car repair or a sudden medical bill, your priority is liquidity and speed. In this scenario, the complexity of a traditional bank or the membership requirements of a credit union might be a hindrance. You need a solution that works today, not next week.
Conversely, if you are looking to leverage your home’s value to consolidate debt or invest in real estate, you need a partner that understands complex assets. A broker might find you a quick personal loan, but a private bank or a specialized institution like NS Bank can provide the structured credit lines that facilitate significant wealth-building moves. Similarly, if you are looking for a “financial home” where you can grow your savings through specialized accounts and enjoy community-focused perks, the credit union model is the clear winner.
One Nevada
Pros:
- Member-focused credit union model.
- Offers specific auto loan benefits like 90-day no-pay periods.
- Lower rates than national banks.
Cons:
- Requires membership to access full benefits.
- Less focus on immediate, high-speed digital funding compared to brokers.
NevLoans
Pros:
- Fast 24-hour funding.
- Soft credit check for rates won’t impact credit score.
- Covers all 14 Nevada cities.
Cons:
- Acts as a connector rather than a direct lender.
- Loan amounts are capped at $35,000.
NS Bank
Pros:
- FDIC insured and backed by the U.S. Government.
- Specialized services for wealth management and home equity.
- High-tier account options like Gold Accounts.
Cons:
- Not focused on quick, small-dollar personal loans.
- Service model is more complex and less geared toward immediate liquidity.
Which one should you choose
If you’re a Nevada resident who needs money fast, maybe for an emergency or a quick home repair, and you want to check your eligibility without hurting your credit score, NevLoans is the most efficient choice. Their 24-hour funding is built for exactly that. It is the ideal “emergency” option for those who prioritize speed and minimal credit impact.
If you want to build a long-term relationship with a local institution and you value community banking, One Nevada is the better fit. They’re ideal if you want more than just a quick loan and want the specific perks that come with a credit union, such as specialized auto loan terms and competitive local rates.
If you need sophisticated banking, are managing significant wealth, or want to tap into your home’s equity, NS Bank is the right option. They aren’t a “quick loan” provider; they’re a full-service bank for people managing a larger financial picture who require highly personalized, high-level service.
Leave a Comment